Quantifi Snaps Up JP Morgan's Pugachevsky
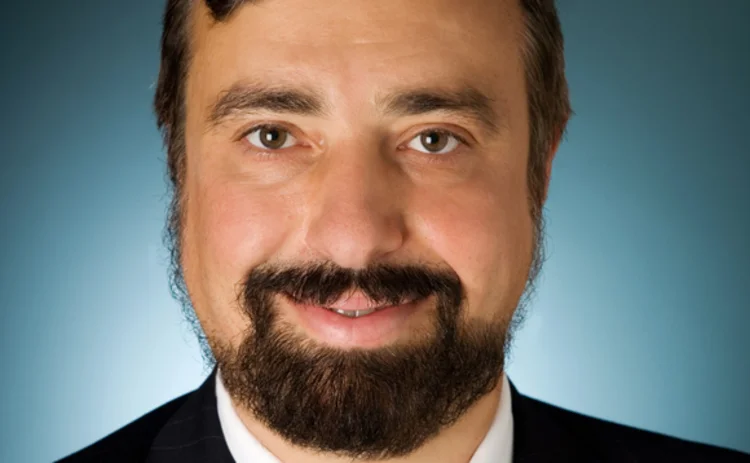
New York-headquartered Quantifi, a provider of analytics, trading and risk management products and services to buy-side and sell-side firms, has appointed Dr. Dmitry Pugachevsky as research director. Pugachevsky, who joins Quantifi from JP Morgan, where he was head of counterparty credit modeling, will be responsible for managing the firm's global research efforts.
Pugachevsky brings more than 18 years' counterparty credit and cross-asset modeling experience to Quantifi. He joins the vendor from JP Morgan, where he responsible for developing new models for calculating CVA (credit value adjustment) across different asset classes and supporting credit portfolio trading.
Before starting with JP Morgan in 2008, Pugachevsky was global head of credit analytics at Bear Stearns for seven years, responsible for modeling a range of credit instruments. Prior to that, he worked for eight years with the analytics groups of Bankers Trust and Deutsche Bank, developing models for credit, fixed income and equity derivatives.
Pugachevsky received his PhD in applied mathematics from Carnegie Mellon University.
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@waterstechnology.com or view our subscription options here: https://subscriptions.waterstechnology.com/subscribe
You are currently unable to print this content. Please contact info@waterstechnology.com to find out more.
You are currently unable to copy this content. Please contact info@waterstechnology.com to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@waterstechnology.com
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@waterstechnology.com
More on Emerging Technologies
Bloomberg launches CLO data solution, Alibaba Cloud expands, and more
The Waters Cooler: A recap of the major tech and data news from the past week in the capital markets.
GPU compute derivatives are put to the test
Interest rates and onions of the past haunt what could be a booming new index market.
The GPU compute index race begins
Major exchanges are partnering with a new crop of benchmark providers to create a tradable asset class around GPU compute.
Agents are invading. Will it stick?
The Waters Wrap: Agentic features are becoming commonplace in the workflow tools of capital markets. Nyela wonders if the trend is sustainable.
TS Imagine launches new agentic platform
TSIQ can act based on client queries, using built-in agent “personas” that can be modified by users on a case-by-case basis.
BBH’s new tech affiliate, Broadridge’s tokenization platform, and more
The Waters Cooler: A recap of the major tech and data news from the past week in the capital markets.

Waters Wavelength Ep. 358: Tradeweb’s Chris Bruner
This week, Tradeweb’s chief product officer joins the podcast to discuss fixed income, prediction markets, agentic AI, and overnight trading.
Can AI beat exceptions out of the back office?
The Waters Wrap: Agentic AI can help operations teams tackle exceptions. But first, they need to get their house in order, writes Wei-Shen.